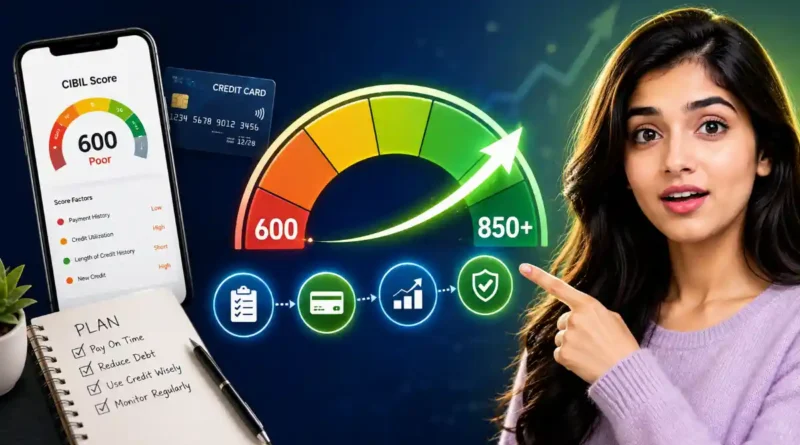
How to Increase CIBIL Score from 600 to 850+: A Complete Step-by-Step Guide
A CIBIL score of 600 can feel like a locked door. Banks hesitate to approve your loans, credit card applications get rejected, and even when you do get approved, you end up paying a much higher interest rate than someone with a stronger score.
The good news is that your CIBIL score is not fixed in stone. With consistent effort and the right financial habits, it is entirely possible to move from a mediocre 600 to an excellent 850. This guide walks you through exactly how to do that, step by step.
Understanding What a CIBIL Score Really Means
Your CIBIL score is a three-digit number ranging from 300 to 900, calculated by TransUnion CIBIL based on your credit history. It reflects how responsibly you have borrowed and repaid money in the past. Lenders use this number to judge how risky it would be to lend to you.
A score below 650 is generally considered poor, 650 to 749 is fair, 750 to 799 is good, and anything above 800 is considered excellent. If you are currently sitting at 600, your goal should be to systematically climb through each of these bands rather than expecting an overnight jump.
Step 1: Get Your Credit Report and Check for Errors
Before making any changes, pull your latest credit report from CIBIL or a trusted platform. Many people are surprised to discover errors in their report, such as loans that were already closed but still show as active, incorrect payment history, or accounts that don’t even belong to them due to identity mix-ups.
Go through every entry carefully. If you spot a mistake, raise a dispute with CIBIL directly through their online portal. Correcting even one inaccurate entry can sometimes boost your score by a noticeable margin, since errors often drag the score down unfairly.
Step 2: Never Miss a Payment Again
Payment history is the single biggest factor influencing your CIBIL score, accounting for roughly 30 to 35 percent of the calculation. A single missed EMI or credit card payment can pull your score down significantly, and the damage lingers for months.
Set up auto-debit for all your loan EMIs and credit card bills so you never miss a due date by accident. If auto-debit isn’t possible, set calendar reminders a few days before each due date. Going forward, treat every payment deadline as non-negotiable. Even one late payment can undo months of improvement work.
Step 3: Reduce Your Credit Utilization Ratio
Credit utilization refers to how much of your available credit limit you are actually using. If your credit card limit is ₹1,00,000 and you consistently carry a balance of ₹80,000, your utilization ratio is 80 percent, which is very high and signals financial stress to lenders.
The ideal utilization ratio is below 30 percent. To bring your ratio down:
- Pay off credit card balances in full each month instead of paying only the minimum due.
- Request a credit limit increase from your bank, which automatically lowers your utilization percentage as long as your spending stays the same.
- Spread your expenses across multiple cards instead of maxing out just one.
Lowering utilization is one of the fastest ways to see a visible improvement in your score within just a couple of billing cycles.
Step 4: Don’t Close Old Credit Accounts
It might seem logical to close an old credit card you no longer use, but this can actually hurt your score. The length of your credit history matters, and older accounts demonstrate a longer track record of responsible credit use. Closing an old account also reduces your total available credit, which can push your utilization ratio higher.
Instead of closing old cards, keep them active with occasional small purchases and pay them off promptly. This keeps your credit history intact while still demonstrating responsible usage.
Step 5: Maintain a Healthy Mix of Credit
CIBIL looks favorably on a balanced combination of secured loans, such as home loans or car loans, and unsecured credit, such as credit cards or personal loans. If your credit profile consists entirely of unsecured debt, it can appear riskier to lenders.
You don’t need to take on new debt just to diversify your profile artificially. Instead, be mindful that if you do need to borrow for a genuine reason, a secured loan can actually help balance your credit mix over time.
Step 6: Limit New Credit Applications
Every time you apply for a new loan or credit card, the lender performs a hard inquiry on your credit report. Multiple hard inquiries within a short period signal to lenders that you may be desperate for credit, which can lower your score.
Be selective about when and where you apply. Space out your applications, and avoid applying to several lenders simultaneously just to compare offers. Use pre-approved offers or soft-inquiry eligibility checks whenever available, since these do not affect your score.
Step 7: Clear Outstanding Debts Strategically
If you are juggling multiple loans or credit card dues, prioritize clearing high-interest debt first, typically credit card balances, followed by personal loans. Consider the debt avalanche method, where you focus extra payments on the highest-interest debt while paying minimums on the rest, or the debt snowball method, where you clear the smallest balances first for psychological momentum.
If your debt has become unmanageable, consider consolidating multiple debts into a single loan with a lower interest rate. This simplifies repayment and can prevent missed payments that would otherwise damage your score further.
Step 8: Become an Authorized User or Use a Secured Card
If your credit history is thin or damaged, ask a family member with excellent credit to add you as an authorized user on their credit card. Their positive payment history can reflect positively on your report.
Alternatively, a secured credit card, backed by a fixed deposit, is an excellent tool for rebuilding credit from scratch. Use it responsibly for small purchases and pay the bill in full every month to steadily build a positive track record.
Step 9: Monitor Your Progress Regularly
Track your CIBIL score every one to two months rather than obsessively checking daily. Checking your own score through official channels counts as a soft inquiry and does not affect your rating. Regular monitoring helps you catch problems early and stay motivated as you watch the number climb.
Step 10: Be Patient and Consistent
Reaching 850 from 600 is not a sprint; it is a marathon that typically takes anywhere from twelve to twenty-four months of disciplined financial behavior, depending on your starting point and the severity of past issues like defaults or settlements. There are no legitimate shortcuts, and anyone promising an instant score boost for a fee is likely running a scam.
Realistic Timeline Expectations
- 0 to 3 months: Correcting report errors and stopping any ongoing late payments can produce an early bump.
- 3 to 6 months: Reduced credit utilization and consistent on-time payments start showing measurable improvement.
- 6 to 12 months: Your score typically moves into the “good” range of 700 to 750 with sustained good habits.
- 12 to 24 months: With continued discipline, a healthy credit mix, and low utilization, scores in the 800s become achievable.
Conclusion
Improving your CIBIL score from 600 to 850 is entirely achievable, but it demands consistency rather than quick fixes. Focus on the fundamentals: pay every bill on time, keep your credit utilization low, avoid unnecessary loan applications, and maintain a healthy mix of credit accounts. Over time, these disciplined habits compound into a credit score that opens doors to better loan terms, lower interest rates, and greater financial freedom.