CIBIL Score Ranges Explained: What Is a Good Credit Score in 2026?
If you have ever applied for a loan or a credit card in India, chances are you have come across the term “CIBIL score.” It is one of those three-digit numbers that quietly decides a lot about your financial life — whether a bank approves your home loan, how much interest you end up paying, and even how quickly your credit card application gets processed. Yet, despite how important it is, many people still don’t fully understand what the number actually means.
In this article, we will break down CIBIL score ranges in simple terms, explain what counts as a good score in 2026, and share practical tips to help you build and maintain a healthy credit profile.
What Exactly Is a CIBIL Score?
CIBIL, short for Credit Information Bureau (India) Limited, is one of the four credit bureaus authorised by the Reserve Bank of India to collect and maintain credit-related data. Your CIBIL score is a three-digit number, ranging from 300 to 900, that summarises your credit history and repayment behaviour.
This number is calculated using information from your credit report, which includes details like your loan accounts, credit card usage, repayment history, outstanding balances, and the number of times you have applied for credit. Banks and non-banking financial companies (NBFCs) use this score to quickly assess how risky it might be to lend you money.
The higher your score, the more trustworthy you appear to lenders. A low score, on the other hand, signals higher risk, which usually means either rejection or approval with unfavourable terms like higher interest rates.
Understanding the CIBIL Score Ranges
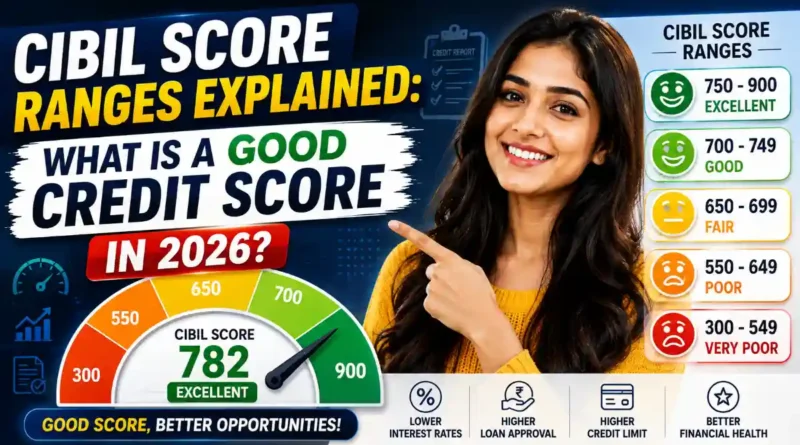
Not all scores are treated equally, and lenders generally group them into distinct categories. Here’s a breakdown of what each range typically means:
300–549: Poor
This is considered a weak score. If your score falls in this bracket, it usually means you have missed payments, defaulted on loans, or have very little credit history to evaluate. Getting a loan approved with a score this low is difficult, and if approved, it often comes with high interest rates and strict conditions.
550–649: Fair
A fair score suggests there have been some slip-ups in your repayment history, but nothing too severe. Lenders may still approve your application, though you might face higher interest rates or lower loan amounts compared to someone with a stronger score.
650–749: Good
This range is considered reasonably healthy. Most lenders will approve loans and credit cards for applicants in this bracket, though the interest rates offered might not be the most competitive ones available in the market.
750–900: Excellent
This is the range most people aim for. A score above 750 tells lenders that you are a low-risk borrower with a solid track record of timely repayments. People in this bracket typically enjoy quicker approvals, higher loan amounts, and the best possible interest rates.
What Counts as a Good CIBIL Score in 2026?
As lending practices evolve and competition among banks increases, the benchmark for a “good” score has become more nuanced. In 2026, most major banks and NBFCs consider anything above 750 as a strong score for securing favourable loan terms. However, several lenders now use more refined, data-driven risk models, meaning even scores in the 700–749 range can get decent approval odds, especially for smaller loan amounts or secured credit products.
That said, if you are planning to apply for a big-ticket loan such as a home loan or a large personal loan, aiming for a score of 750 or above is still the safest bet. It not only increases your chances of approval but can also help you negotiate a lower interest rate, which translates into real savings over the loan tenure.
Factors That Influence Your CIBIL Score
Understanding what affects your score can help you manage it more effectively. Here are the key factors:
Payment history carries the most weight. Consistently paying your EMIs and credit card bills on time has the single biggest positive impact on your score. Even one missed payment can cause a noticeable dip.
Credit utilisation ratio refers to how much of your available credit limit you are using. Ideally, keeping this below 30 percent shows lenders that you are not overly dependent on borrowed money.
Length of credit history matters too. A longer history of responsible credit use generally works in your favour, since it gives lenders more data to assess your reliability.
Credit mix — having a healthy combination of secured loans (like a home or car loan) and unsecured credit (like credit cards or personal loans) can positively influence your score, as it shows you can manage different types of credit responsibly.
Number of credit inquiries also plays a role. Applying for multiple loans or credit cards within a short span can lower your score, as it may signal credit hunger to lenders.
How to Improve or Maintain a Good CIBIL Score
Building a strong score doesn’t happen overnight, but consistent habits can make a real difference over time.
Start by paying all your bills and EMIs on or before the due date. Setting up auto-debit instructions can help you avoid accidental delays. Try to keep your credit card usage well within your limit rather than maxing it out every month, even if you plan to pay it off in full later.
Avoid applying for multiple loans or credit cards in a short period, as each application triggers a hard inquiry that can temporarily lower your score. Instead, space out your applications and only apply when you genuinely need credit.
It also helps to periodically check your credit report for errors. Sometimes, incorrect information — like a loan that was already closed but still shows as active — can drag your score down unfairly. If you spot such discrepancies, raise a dispute with the credit bureau to get them corrected.
Lastly, if you have old, unused credit cards, think twice before closing them. Keeping them active (even with minimal usage) can help maintain a longer credit history and a healthier credit utilisation ratio.
Conclusion
Your CIBIL score is more than just a number — it’s a reflection of your financial discipline and a key that can unlock better borrowing opportunities. Understanding where you stand within the CIBIL score ranges, and what lenders expect in 2026, puts you in a much stronger position when it comes to managing loans, credit cards, and overall financial planning.
The good news is that improving your score is entirely within your control. With consistent, responsible credit habits — timely payments, sensible credit utilisation, and regular monitoring of your credit report — you can steadily move toward that coveted “excellent” range and enjoy the financial flexibility that comes with it.